For most of the last decade, the carbon black story was fairly simple: capacity grew, mostly in Asia, while the West gradually gave up share. That version is still directionally true, but it has stopped being sufficient. Developments across China, the West, India and Egypt in 2026 suggest something more complicated is happening. The carbon black industry is not simply expanding or contracting. It is re-sorting itself by cost position, product grade and proximity to customers.
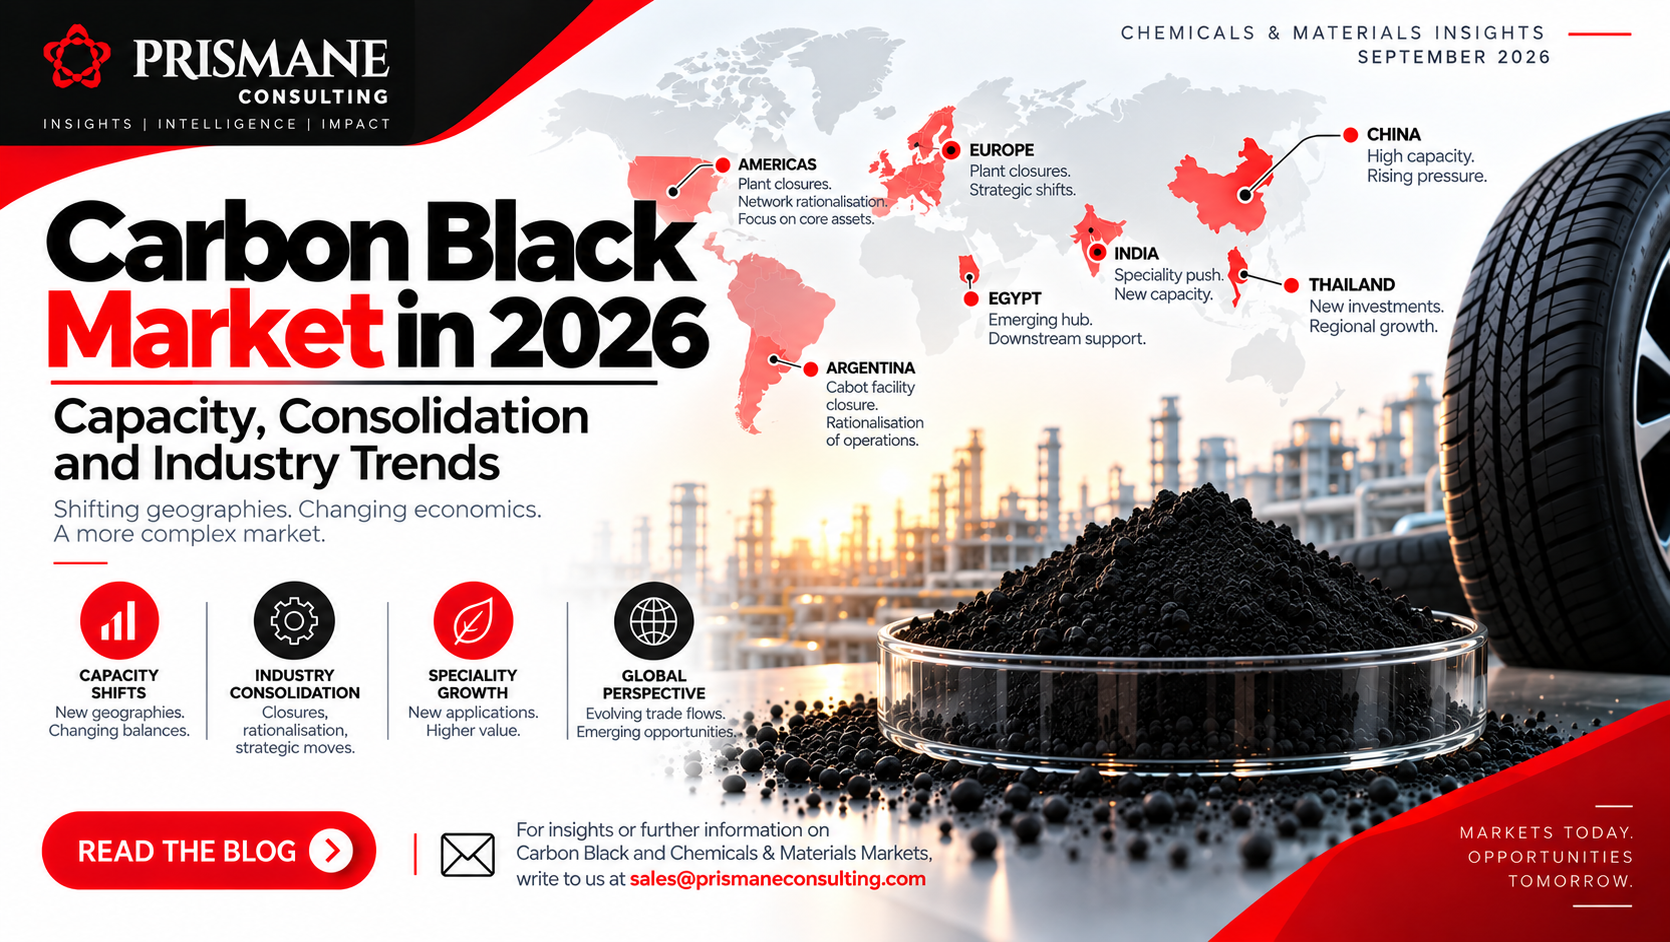
That re-sorting is becoming visible across the supply chain. China continues to add large volumes of capacity despite deteriorating profitability. Producers in North America and Europe are responding to difficult operating economics by closing or rationalising selected production lines. India is moving further into speciality carbon black while also attracting new conventional capacity. Thailand is emerging as another location for customer-led capacity expansion, while Egypt is positioning itself as a new regional carbon black production base alongside growing tyre manufacturing investment.
The result is a carbon black market in which the location and quality of capacity are becoming almost as important as its total volume.
China's carbon black scale is no longer enough
Chinese effective carbon black capacity reached 9.4 million tons in 2025, representing close to 46% of global capacity. Yet data covering 30 key carbon black producers showed combined first-quarter revenue of around USD 1.23 billion (Yuan 8.77 billion) alongside an aggregate loss of around USD 29.5 million (Yuan 210 million). The average margin was around negative 2.44%, 16 of the 30 companies were loss-making, and eight of the ten largest companies by revenue were also reporting losses.
The significance of these figures is not simply that profitability weakened during one quarter. They indicate how far capacity scale and industry profitability have become disconnected. Industry data and commentary have increasingly pointed to structural overcapacity, homogeneous competition and pressure from both upstream and downstream markets as major challenges facing China's carbon black sector.
This changes the way China's carbon black capacity needs to be interpreted. Capacity growth itself is no longer an adequate indicator of industry strength. A producer may have access to large-scale manufacturing infrastructure, but if the market cannot absorb additional volumes at sustainable margins, incremental capacity can become a liability rather than an advantage.
The pressure is particularly relevant to conventional carbon black grades, where products can be relatively interchangeable from the customer's perspective. Competition can therefore become heavily price-driven, especially when multiple producers are competing for the same tyre and rubber customers.
Environmental requirements add another layer to the challenge. Carbon black production is energy intensive and closely connected to heavy aromatic feedstocks. As environmental standards and carbon reduction policies become more stringent, producers must increasingly balance production economics with investment requirements for cleaner and more efficient operations.
China will remain central to the global carbon black market. Its manufacturing scale, large tyre industry, chemical infrastructure and export network ensure that it will continue to influence global pricing and trade flows. The issue is that scale alone is becoming less valuable when it is accompanied by structural overcapacity.
The Western response is closure, not just guidance
While China continues to deal with excess capacity, producers in mature Western markets are taking a different approach. Selected production lines are being closed, consolidated or repositioned as companies reassess which assets can generate sustainable returns.
Orion has announced plans to discontinue several carbon black lines across the Americas and EMEA, concentrating investment on better-performing assets. Cabot has also confirmed the closure of its Campana facility in Argentina and has been rationalising parts of its production network. These actions point towards a broader reassessment of carbon black manufacturing footprints in regions where operating costs, environmental requirements and mature downstream markets can make selected assets increasingly difficult to justify.
The important point is that this does not necessarily represent a collapse in Western carbon black demand. Tyres, rubber goods, plastics and other applications continue to require carbon black. The structural change is taking place primarily on the supply side.
Fewer production lines serving broadly stable demand can eventually alter regional trade flows and customer sourcing patterns. Remaining producers may benefit from higher utilisation, while customers may become more dependent on imports from lower-cost manufacturing regions.
The Western market is therefore moving towards a model in which the competitiveness of individual plants matters more than the total size of regional nameplate capacity.
India is expanding, but the product mix is what matters
Against this backdrop, India's carbon black industry is taking a different direction.
The country already has a substantial carbon black manufacturing base supported by its large tyre industry. However, the investment story is increasingly extending beyond conventional grades towards speciality carbon black, where product performance and application requirements can support a different competitive structure.
Himadri Speciality Chemical's expansion illustrates this shift. In February 2026, the company commissioned a 70-kiloton speciality carbon black line at its Mahistikry facility in West Bengal, taking total carbon black capacity to around 250 kilotons and speciality capacity to around 130 kilotons.
The significance of this investment goes beyond the additional tonnes. Speciality carbon black is used in applications where dispersion, conductivity, colour characteristics, reinforcement, purity and other performance parameters can be more important than simply achieving the lowest price per ton.
That creates an opportunity for Indian producers to reduce their exposure to the most commoditised parts of the carbon black market.
The timing is also important. Changes in international trade flows and restrictions on Russian carbon black imports are creating opportunities for alternative suppliers, particularly those with the technical capabilities and production capacity required by speciality applications.
India is therefore developing a carbon black model in which capacity expansion and product differentiation are occurring at the same time.
Birla Carbon is adding new capacity in India and Thailand
The Asian expansion story is not limited to speciality grades.
Birla Carbon is set to start production at two new greenfield carbon black plants in India and Thailand by the end of 2026. Located in Naidupet, Andhra Pradesh, and Rayong, Thailand, the facilities will have an initial combined capacity of approximately 240 kilotons per year, with each plant starting at around 120 kilotons.
Each facility also has the potential to expand towards approximately 240 kilotons as demand develops. That distinction matters. The initial 120-kiloton configuration represents the near-term project capacity, while the additional capacity represents future scalability rather than current operating supply.
The structure provides a useful indication of how major carbon black producers are approaching the next phase of capacity investment. Rather than committing the maximum potential volume immediately, Birla Carbon is establishing manufacturing platforms in strategically important markets and retaining the flexibility to expand as customer demand becomes clearer.
Thailand provides proximity to an established regional tyre and rubber manufacturing ecosystem, while India combines domestic tyre demand with access to export markets. In both cases, location and optionality are doing as much work as the headline capacity number.
This is an important contrast with capacity additions in an already oversupplied market. The objective is not simply to maximise nameplate capacity, but to establish production where there is greater visibility on customers and regional demand while retaining the flexibility to scale as the market develops.
Egypt could create a new competitive carbon black market
Egypt provides another example of new carbon black capacity following downstream investment.
Shandong Link Science & Technology has proposed a carbon black and silica complex in Egypt's Sokhna Industrial Zone, including around 100 kilotons of carbon black capacity. The project is significant because Egypt already has an established domestic carbon black production base.
Egypt currently has a single domestic producer, Birla Carbon Egypt, with around 285 kilotons of capacity tracked in the Prismane Consulting market model. If the proposed Link Science project is commissioned, the country would move from a single domestic production structure to at least two domestic producers. The proposed carbon black capacity would be equivalent to around 35% of Birla Carbon Egypt's existing capacity.
The timing is also notable because Chinese tyre manufacturers including Linglong Tire, ZC Rubber and Sailun are advancing manufacturing investments in Egypt. Carbon black and tyre manufacturing are closely connected, making the development part of a broader localisation trend across the tyre supply chain.
The eventual impact of the proposed capacity will depend on how quickly downstream tyre projects ramp up, the grades produced, operating rates, domestic consumption and the project's export strategy. The additional tonnes could support incremental local demand, replace imports, serve export markets or compete for existing domestic customers.
What matters at this stage is the direction of travel. Egypt is becoming a market where upstream carbon black capacity and downstream tyre manufacturing could develop together rather than independently.
Sustainability is becoming a real point of competition
Another structural change is emerging around sustainability.
Carbon black customers have traditionally evaluated suppliers primarily on cost, consistency, quality and supply reliability. Environmental performance is increasingly being added to that equation as tyre manufacturers and other downstream companies face greater pressure to reduce the footprint of their products.
The development of recovered carbon black is particularly relevant. Producers are increasingly exploring recycled feedstocks and circular production routes that can provide an alternative source of carbon for selected applications.
Recovered carbon black will not simply replace virgin carbon black across the market. Product consistency, technical qualification, processing requirements and application performance remain important constraints. However, the technology introduces another potential basis for differentiation.
This means carbon black producers are increasingly competing across several dimensions at once. Grade, cost position, geographic location, customer relationships and sustainability credentials can all influence a producer's position in the market.
The industry is consequently moving away from a model in which price and volume are the dominant competitive variables.
This is a story Prismane Consulting has been tracking for years
The developments of 2026 did not emerge in isolation. Prismane Consulting has been tracking the structural changes in the carbon black market for several years, particularly the disruption of Russian supply, the changing position of European producers and the emergence of India as an increasingly important supplier to international markets.
Ahead of the EU's ban on Russian carbon black, our analysis examined how the loss of Russian and Belarusian supply could affect European tyre manufacturers and carbon black trade flows. At the time, the key question was whether European producers and alternative suppliers could compensate for the volumes that would disappear from the regional market.
As the deadline approached, the focus shifted towards India. Our analysis identified the potential for Indian carbon black producers to capture part of the displaced European demand, supported by India's growing production base and expanding export capabilities. The analysis also highlighted the potential value of the opportunity, with the replacement of a portion of Russian supply representing a potential export opportunity of more than USD 200 million.
By 2025, the question was no longer simply what might happen after the ban. It was how the market was actually adapting. Our subsequent analysis tracked the movement of European buyers towards suppliers in China and India, the premium attached to reliable local supply and the changing balance between domestic European production and imports.
Those earlier observations provide useful context for what is happening in 2026. The carbon black market is now moving into a broader phase of restructuring, where trade flows, plant economics, speciality grades, regional capacity and downstream customer locations are interacting more closely than before.
The developments being seen today are therefore not a series of isolated capacity announcements. They are the continuation of a supply chain shift that has been visible in carbon black trade and investment patterns for several years.
For Prismane Consulting, this is also why plant-level capacity, trade flows and downstream demand need to be viewed together. Following individual announcements can explain what has happened. Tracking the market continuously helps explain why it is happening.
What this is really showing
Put these developments together and the global carbon black industry does not look like a market that is simply growing or shrinking. It looks like a market that is sorting itself.
China has enormous conventional capacity, but profitability is under pressure as supply continues to expand and competition intensifies. North America and Europe are responding by rationalising selected assets and concentrating production where economics are stronger.
India is moving further into speciality carbon black, while also becoming a destination for new capacity linked to domestic and regional demand. Birla Carbon's projects in India and Thailand add another dimension, with greenfield manufacturing platforms designed around customer growth and staged scalability.
Egypt represents a different opportunity, with proposed new capacity emerging alongside the localisation of tyre manufacturing and broader industrial investment.
These developments may look unrelated when viewed individually. Together, they point towards a carbon black market in which the quality and location of capacity are becoming more important than capacity alone.
The next phase of the industry is therefore unlikely to be defined simply by who adds the most tonnes.
It will increasingly be defined by who has the right tonnes, in the right location, with the right cost structure and the right customer base.
That is particularly important in a market where large-scale capacity can coexist with weak profitability. China's experience demonstrates that adding supply does not automatically create stronger industry economics. At the same time, the expansion strategies emerging in India, Thailand and Egypt show that capacity can still attract capital when there is a clearer connection between production, downstream demand and regional supply chains.
For carbon black producers, the strategic question is becoming more specific: where should the next ton of capacity be built, which grade should it produce, and which customers will support it?
For tyre manufacturers and other carbon black consumers, the changing supply landscape could create new regional sourcing options while also increasing differences between suppliers in terms of cost, product availability and sustainability performance.
For the carbon black market as a whole, 2026 is beginning to look less like another capacity cycle and more like a structural reallocation of manufacturing.
Prismane Consulting tracks carbon black capacity, demand, trade flows and announced projects at the country and plant level, helping assess how changing investment patterns are reshaping global and regional supply. For the full Global Carbon Black Market Study, write to us at sales@prismaneconsulting.com.