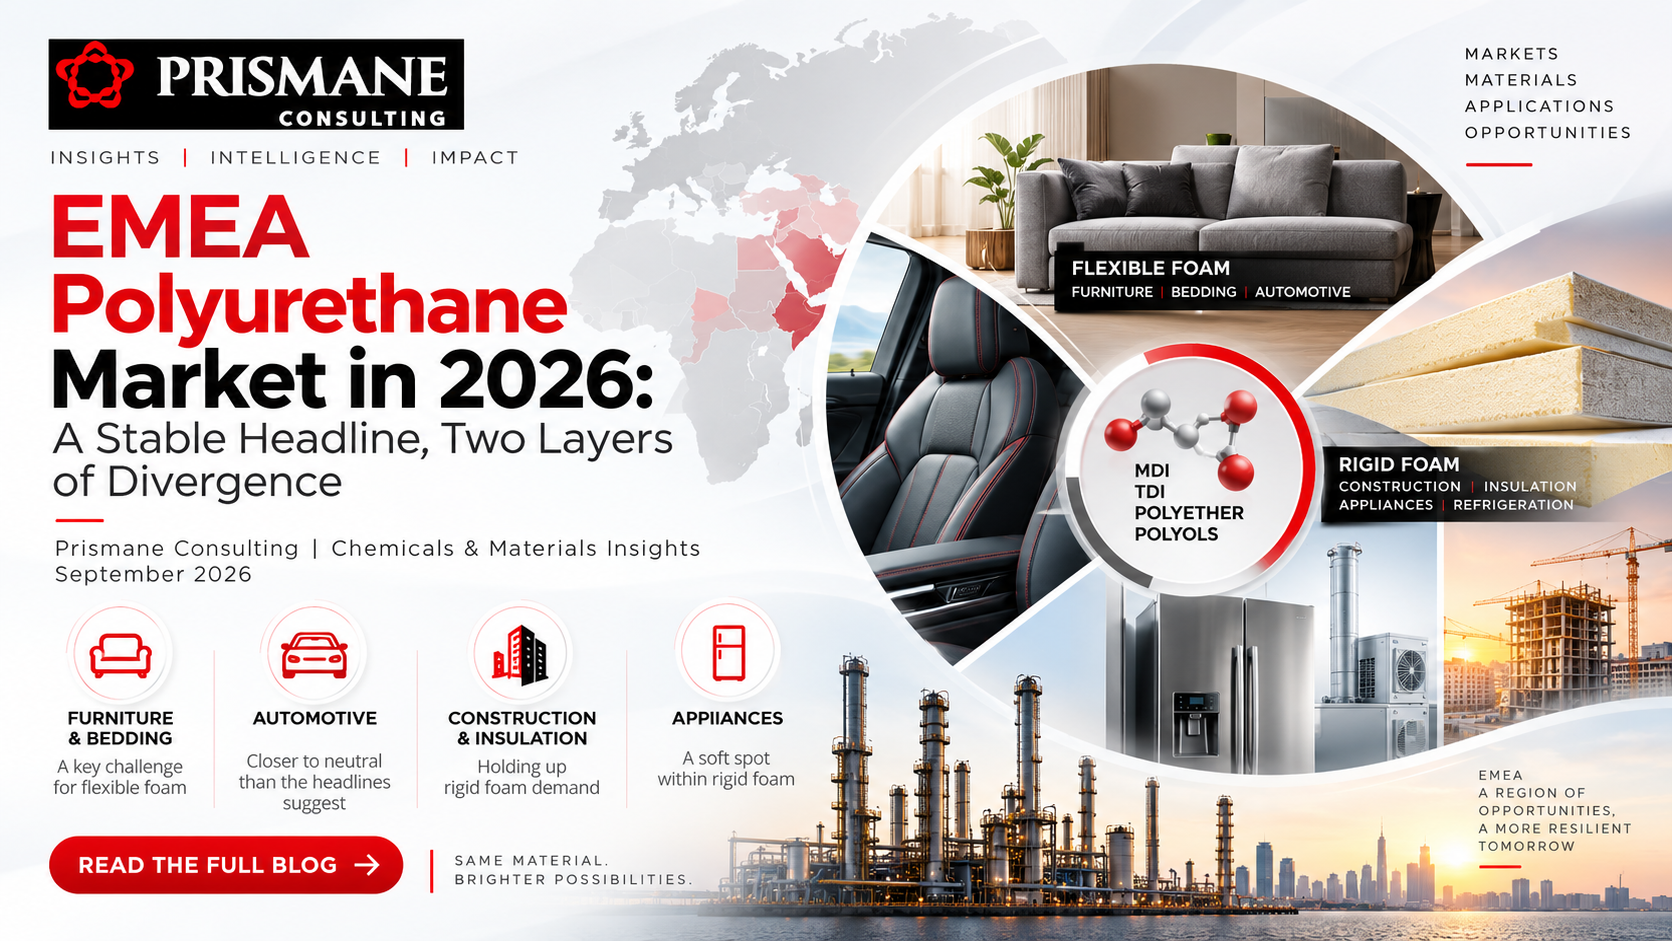
The EMEA polyurethane market has held close to the same broad output level across recent production checkpoints, with flexible and rigid foam running close to parity. Read only at that regional level, the market looks steady. It is not. This piece looks at what is actually driving flexible and rigid foam demand across the EMEA polyurethane market, and what the resulting split means for MDI, TDI and polyether polyols. It does not attempt a full regional supply-demand balance for the three raw materials; that is what Prismane Consulting's dedicated MDI, TDI and Polyether Polyols market studies cover in depth.
A steady regional total is an average, not a sign of balance
Flexible and rigid foam are the two principal demand pools in the EMEA polyurethane market, and the regional total staying broadly flat masks an averaging effect: weakness in some applications and countries is being offset by firmness elsewhere. Flexible foam tracks furniture, mattresses and automotive interiors; rigid foam tracks construction, insulation, appliances and refrigeration. These follow different cycles, so a flat regional number does not signal equilibrium. It can just as easily mean decline in one pool offset by growth in another.
Furniture and bedding are flexible foam's weak spot
Furniture and bedding are flexible foam's largest EMEA outlet, well ahead of automotive. European furniture and mattress production has stayed below its 2022 levels, with upholstered and convertible seating down further than mattresses. Because these two categories carry most of flexible foam's demand, this single channel is doing most of the work in holding the segment back.
This lands directly on TDI and flexible polyether polyols: when furniture and mattress manufacturers stay cautious on production and inventory, demand for the raw materials behind flexible foam stays soft even as producers push prices higher. See Prismane Consulting's Toluene Diisocyanate (TDI) Market for the full regional supply-demand picture.
Automotive is closer to neutral than the headlines suggest
Regional vehicle production has stayed broadly flat, but that hides real divergence at the country level: Germany, Turkiye and South Africa have posted production gains, while Morocco has declined. For flexible foam, that makes automotive look less like a uniform drag and more like a wash at the regional level, with furniture and bedding remaining the clearer source of pressure. A recovery in vehicle production would help flexible foam demand but would not on its own offset the much larger furniture and bedding shortfall.
Rigid foam is holding up on insulation and geography, not on construction alone
Building insulation dominates rigid foam demand. European construction stayed weak through 2025, with recovery only expected to build through 2026 from a low residential base, yet rigid foam overall has held up better than European construction alone would suggest. Part of that is genuine insulation-linked resilience; part of it is regional mix, since the Middle East project pipeline has stayed comparatively firmer and African markets are moving on their own individual project cycles rather than with Europe.
MDI carries more of this insulation and construction exposure than TDI does. See Prismane Consulting's Methylene Diphenyl Diisocyanate (MDI) Market for capacity, trade and regional detail.
Appliances are rigid foam's own soft spot
Rigid foam's resilience is not uniform. Appliances and refrigeration are a smaller share of rigid foam demand than insulation, and that smaller share has weakened compared with 2023, as cooling-appliance production came in lower across several markets. Construction and insulation demand is carrying rigid foam while appliance-linked demand softens within it, the same averaging pattern visible at the regional level one layer up.
What the divergence means for MDI, TDI and polyether polyols
The downstream split carries through to raw materials directly. TDI and flexible polyether polyols sit closer to the furniture-driven weakness; MDI sits closer to the insulation-driven strength; and polyether polyols straddle both sides of the value chain, so their demand signal depends on which side is pulling harder in a given quarter. See Prismane Consulting's Polyether Polyols Market for the full picture, and our earlier analysis, Polyether Polyols Price Middle East Conflict: The Quiet Casualty Reshaping Global PU Supply, for how the Middle East conflict specifically reshaped polyol pricing.
The Sadara complex in Jubail, the Aramco-Dow joint venture and one of the few Middle East facilities producing MDI, TDI and polyether polyols directly, adds a further supply-side variable. Sadara halted all production at the complex at the end of March 2026 as the Hormuz-related conflict disrupted its feedstock and export routes, with no restart timeline given at the time. MDI and polyol output has since come back online, but only gradually: full production is not expected until 2027, and a restart date for TDI specifically has not been confirmed. Separately, Dow is reviewing options for its 35% stake in the venture, including a possible full exit, with Aramco or another investor as potential buyers; no final decision has been made as of this writing. Either the slow ramp-up or a change in ownership affects how much Middle East-origin MDI, TDI and polyol supply reaches the EMEA polyurethane market in the near term, layering supply-side uncertainty on top of the demand-side divergence described above.
Pricing and trade signals worth watching
Producer pricing is not settling the demand question either way. BASF raised MDI and TDI prices by $250 per ton across ASEAN and South Asia on September 11, the latest in a run of regional increases since July that also touched Southeast Asia, the Middle East, Africa and Turkiye, and BorsodChem adjusted its MDI, TDI and polyol lines in Europe in August. See Prismane Consulting's MDI & TDI in September 2026: Prices Rise as Demand Stays Cautious for the pricing side in full. A producer can raise prices on tighter supply and higher input costs while furniture, mattress and appliance production stays below prior levels, which is exactly the pattern the EMEA polyurethane market is showing right now, and it is the same distinction we drew in The Polyurethane Industry Isn't Recovering: It's Repricing Risk.
Chinese export flows add a variable specific to TDI: China's TDI exports ran close to a quarter higher year on year in the first half of 2026, and Belgium was among the top destinations, so cheaper Chinese material is already reaching parts of Europe and will limit how far EMEA producers' own increases can hold.
What it means
EMEA polyurethane demand splits along two layers: flexible versus rigid foam, and a second split inside each segment. Furniture and bedding are pulling flexible foam down while automotive is roughly a wash; insulation and construction are holding rigid foam up while appliances soften within it; and geography adds a third layer, with the Middle East and parts of Africa behaving differently from the European core. Raw materials inherit the same split, and Sadara's slow restart and Dow's ownership review add a further supply-side wildcard on top of it, while producer price increases and rising Chinese TDI exports pull in opposite directions on what buyers actually pay. The practical question for the rest of 2026 and into 2027 is not whether the EMEA polyurethane market is recovering. It is which application, in which part of the region, actually is, and which raw material sits behind it.
Prismane Consulting tracks the EMEA polyurethane market, across flexible foam, rigid foam and the underlying MDI, TDI and polyether polyols raw material base, through its Chemicals Practice. For more on how these dynamics affect your specific sourcing or demand outlook, get in touch with Prismane Consulting at sales@prismaneconsulting.com.